
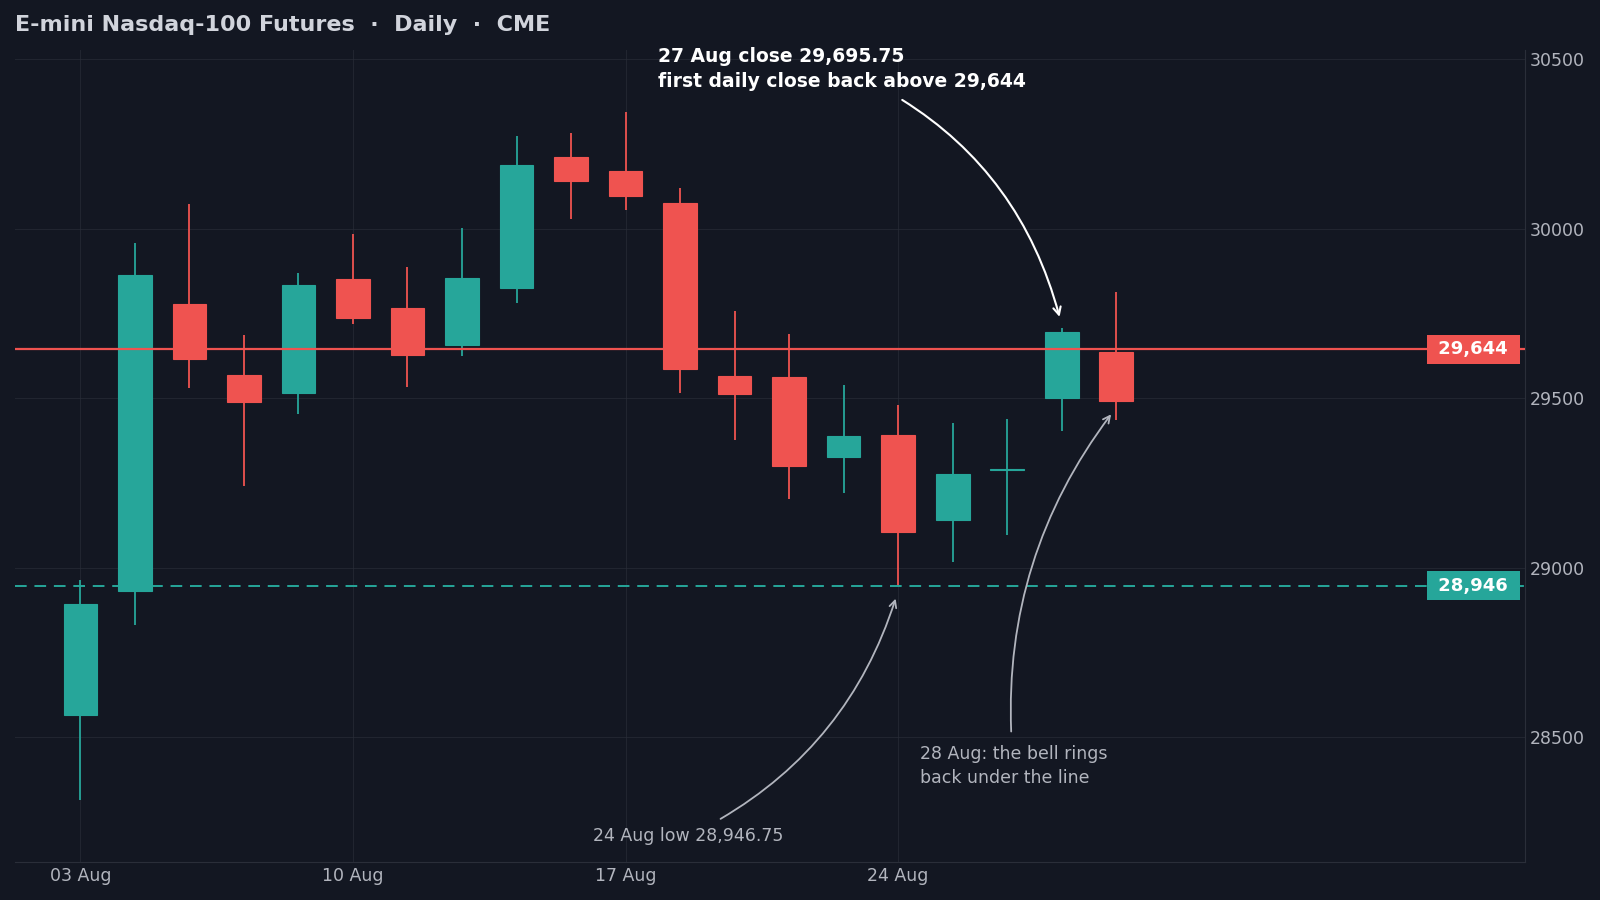
Monday I wrote down a short plan for NQ and, more importantly, what would kill it: sell the bounce into 29,644, target 28,946, thesis dead on any daily close back above 29,644.
Monday skipped the bounce and went straight to the target: 28,946.75, three quarters of a point from my number, with my offer at 29,644 untouched the whole way down. Watching your target print without you is its own special punishment.
The fill finally came Wednesday evening, a few hours after Nvidia's numbers, into the squeeze. One session later the trade was dead by its own rule: Thursday settled 29,695.75, fifty-odd points above my line, which is all a line ever needs to be. Trapped buyers, supply into every bounce - none of it was true any more, and it didn't get less untrue for being well argued.
Then Friday gave the whole reclaim back and rang the bell under the line. The order never read my post-mortem: parked with a far stop and valid to the Friday close, it came out roughly 135 points onside. The thesis was falsified Thursday, the P&L went green Friday. Same trade, both true.
The short had a macro leg too: long yields climbing, a September hike creeping back onto the table. All of it downstream of jobs numbers that turn out to be a draft - February's benchmark quietly deleted 862,000 jobs from the record, and Friday morning's first pass at the next one shaved off another 79,000. A year of traders sizing up on an economy that didn't exist as printed.
And here's the trap. The voice that spent Thursday whispering "it's an earnings gap, it doesn't really count" just got paid. It will quote this week at me for years.
Disclosure - I trade NQ. The short above was mine; I was also long intraday Thursday.
If you can't name the price that makes you wrong before you click buy, you've got an opinion with leverage on it. And when a dead opinion pays you anyway, don't you dare learn from it.
Not financial advice · education only. Manage your own risk.